What could your savings pay you every month?
An instant, before-tax estimate of lifetime income from a single premium immediate annuity (SPIA). No contact info needed.
Your estimate will appear here.
Fill in what you know and press See my estimate. Nothing is saved and no contact info is needed.
Common questions
How much does a $100,000 annuity pay per month at age 65?
At age 65, life only, before tax: about $655–$700 a month for a man and $622–$665 a month for a woman, for life, starting about a month after purchase. Estimates are modeled from published carrier quote surveys as of October 1, 2026; exact quotes vary by carrier, state, and premium size.
How much does a $250,000 annuity pay per month at age 65?
About $1,639–$1,750 a month for a man and $1,555–$1,661 a month for a woman at age 65, life only, before tax — paid every month for life. Run the estimator above with your own age and amount for your personalized range.
How much does a $500,000 annuity pay per month at age 65?
About $3,277–$3,500 a month for a man and $3,111–$3,323 a month for a woman at age 65, life only, before tax, for life.
What does adding a guarantee cost?
A guarantee trades a little monthly income for protection for your family. Estimated monthly income before tax — a 65-year-old man with $250,000: life only pays $1,639–$1,750 a month; life with 10 years certain pays $1,574–$1,681, and your beneficiary receives the remaining payments in the initial 10-year period if you die within it; life with cash refund pays $1,557–$1,662, and your beneficiary receives the premium paid minus payments already received, if any balance remains.
When do payments start, and how long do they last?
The estimates here start income about one month after purchase. Life payments continue every month for as long as you live — even past age 100. Our joint-life estimates assume 100% of the payment continues to the surviving spouse; other survivor percentages may be available.
Are annuity payments taxed?
All estimates here are before tax. With an income annuity bought using after-tax savings, payments generally include taxable income and a tax-free return of your investment until that investment is recovered; later payments are generally fully taxable. Payments funded entirely with pretax traditional IRA money are generally taxable as ordinary income. Qualified Roth IRA distributions are federally tax-free. After-tax IRA contributions and other circumstances can change the treatment. This is general information, not tax advice — IRS Publications 939 and 590-B cover the details.
Where do these estimates come from?
They are modeled from published carrier quote surveys as of October 1, 2026. The survey publishes 5-year period-certain payouts; we model the other payout options from it, so these are not the survey’s published figures for those options. The low end of each range is modeled from the survey’s 8-carrier average and the high end from its best quote. The surveyed carriers are a market benchmark, not a list of carriers we represent. See “How these estimates are calculated” for the full method. We refresh the figures monthly.
Do I need to give my phone number to see results?
No. Your estimate appears right away with no name, email, or phone required. You only share contact details if you want us to email the estimate or request personalized quotes.
Why does age change the payout so much?
Lifetime income is priced on how long payments are expected to last. The older you are when income starts, the fewer expected years of payments, so each monthly payment is larger.
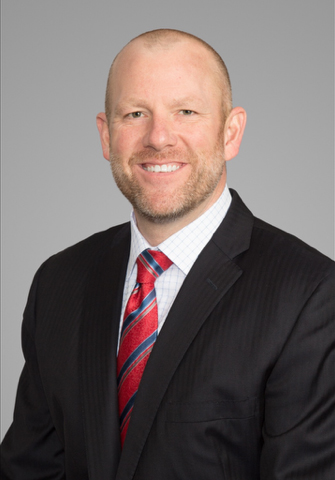
Meet the person who'll call you
Ron Hensel
President
Ron Hensel is President of InsurTech Express and the licensed agent behind ITX Insurance Agency. He brings more than 24 years of deep industry expertise and firsthand insight into helping clients protect their hard-earned assets and plan for a more secure retirement. His experience includes senior annuity leadership roles at The Hartford and Global Atlantic Financial Group, where his division raised more than $30 billion in annuity premiums. Ron lives in Chesterfield, Missouri, with his wife, Charlotte, and their three sons.
We return messages during business hours, usually the same day. No obligation, ever. How we’re paid