The three honest risks: inflation, liquidity, and early death

An income annuity solves one big risk — outliving your money. It brings three others you should weigh honestly.

1. Inflation

Most SPIA payments are level. At 3% inflation, a fixed check buys about a quarter less after 10 years and about 45% less after 20. Social Security, by contrast, gets a cost-of-living adjustment most years.

  • Some carriers offer payments that rise by a set percentage each year, in exchange for a lower starting check.
  • Many people annuitize only part of their savings and keep the rest invested for growth.
  • Others buy in stages — one SPIA now, another a few years later.

2. Liquidity

Once you buy, you generally can’t get the lump sum back. Keep an emergency fund separate, and don’t annuitize money you may need for large expenses.

3. Dying early

With life-only income, payments stop at death — even if that’s soon after you buy. Guarantee options (period certain or cash refund) protect your heirs for a modest reduction in income. Compare guarantee options.

Context: by the SSA’s 2023 period life table, a 65-year-old man’s average life expectancy is about 83.1 and a 65-year-old woman’s about 85.7 — and averages mean many people live well past them.
Common questions

Do annuity payments keep up with inflation?

Most SPIA payments are level and do not. Some carriers offer payments that increase by a set percentage each year in exchange for a lower starting payment.

What if I die soon after buying an annuity?

With life-only income, payments stop. A period-certain or cash-refund guarantee passes remaining payments or unpaid premium to your beneficiaries.

See what your savings could pay you — every month, for life.

Free estimate in under a minute. No name, email, or phone needed to see your result.

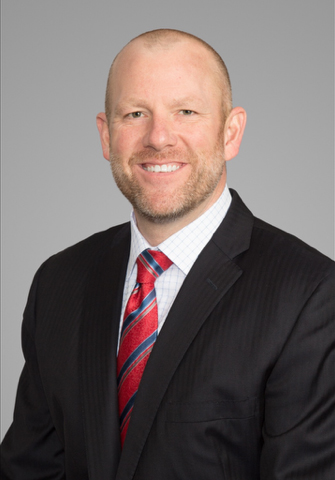
Photo of Ron Hensel
Talk to a real person

Meet the person who'll call you

Ron Hensel
President

Ron Hensel is President of InsurTech Express and the licensed agent behind ITX Insurance Agency. He brings more than 24 years of deep industry expertise and firsthand insight into helping clients protect their hard-earned assets and plan for a more secure retirement. His experience includes senior annuity leadership roles at The Hartford and Global Atlantic Financial Group, where his division raised more than $30 billion in annuity premiums. Ron lives in Chesterfield, Missouri, with his wife, Charlotte, and their three sons.

We return messages during business hours, usually the same day. No obligation, ever. How we’re paid

Free download

The Free SPIA Buyer’s Guide

A short, plain-English guide to income annuities: how they work, what to compare, and the questions to ask any seller. Email only — no phone number needed.

We never sell your information. Unsubscribe any time.