Buying an annuity with IRA money vs savings

The annuity can be identical. The taxes on each check are not.

With IRA or 401(k) money (qualified)

  • Every payment is taxable as ordinary income, because the money was never taxed going in.
  • Move it directly. A direct (trustee-to-trustee) transfer or rollover into an IRA annuity avoids withholding and penalties. Taking a check yourself starts a 60-day clock.
  • Required minimum distributions. Payments from an annuity held in an IRA can generally count toward the RMD for that IRA.

With savings (non-qualified)

  • Part of each payment is tax-free — the return of money you already paid tax on — using the IRS exclusion ratio.
  • Once you’ve recovered your full investment, later payments are fully taxable.
  • See a worked example.

Roth money

Qualified Roth distributions are generally tax-free, and Roth IRAs have no RMDs for the original owner — so many people prefer to spend other money first. Ask your tax professional.

All our estimates are shown before tax. Your actual after-tax income depends on where the money comes from and your tax situation.

General information, not tax advice. Your tax professional can tell you how this applies to you.
Common questions

Can I roll my 401(k) into an annuity?

Yes. A direct rollover or trustee-to-trustee transfer from a 401(k) or IRA into an IRA annuity keeps the money tax-deferred. Payments are then taxed as ordinary income.

Is annuity income from savings taxed?

Partly. With non-qualified savings, part of each payment is a tax-free return of your investment based on the exclusion ratio; the rest is taxable.

See what your savings could pay you — every month, for life.

Free estimate in under a minute. No name, email, or phone needed to see your result.

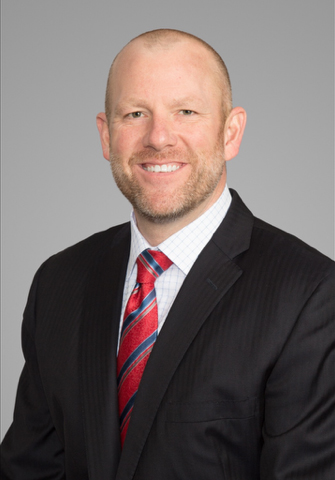
Photo of Ron Hensel
Talk to a real person

Meet the person who'll call you

Ron Hensel
President

Ron Hensel is President of InsurTech Express and the licensed agent behind ITX Insurance Agency. He brings more than 24 years of deep industry expertise and firsthand insight into helping clients protect their hard-earned assets and plan for a more secure retirement. His experience includes senior annuity leadership roles at The Hartford and Global Atlantic Financial Group, where his division raised more than $30 billion in annuity premiums. Ron lives in Chesterfield, Missouri, with his wife, Charlotte, and their three sons.

We return messages during business hours, usually the same day. No obligation, ever. How we’re paid

Free download

The Free SPIA Buyer’s Guide

A short, plain-English guide to income annuities: how they work, what to compare, and the questions to ask any seller. Email only — no phone number needed.

We never sell your information. Unsubscribe any time.